Executive Summary: Synthesis of the Ceramic Wall Tiles Market
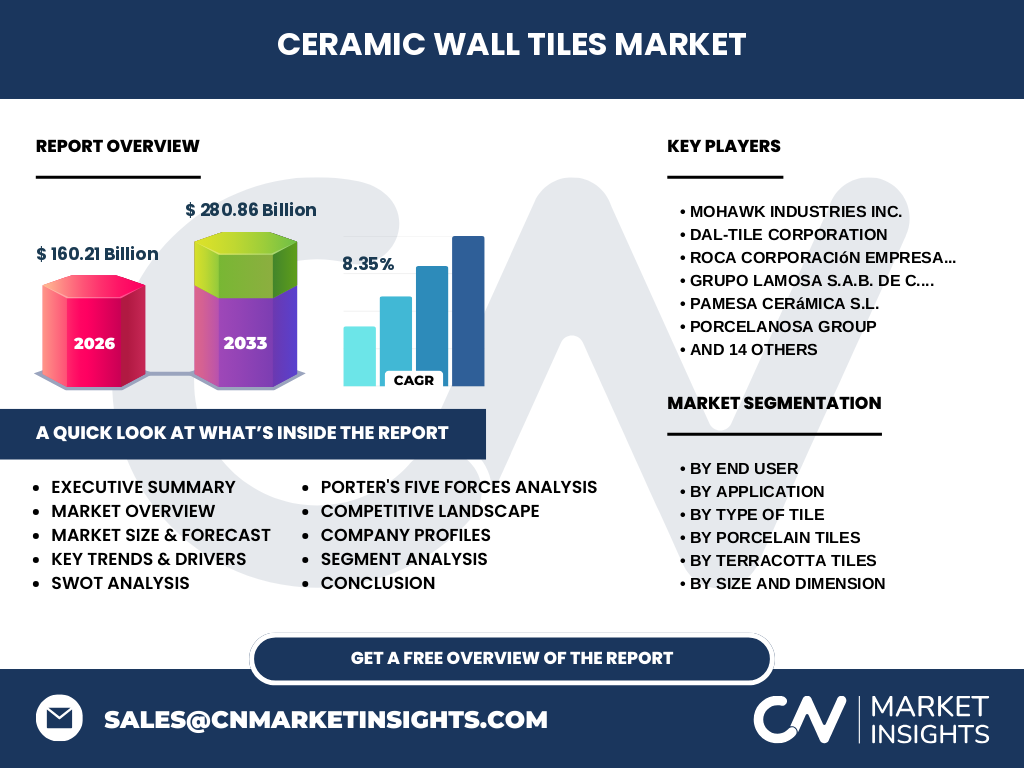
The Ceramic Wall Tiles Market is poised for substantial expansion, reaching a projected valuation of $280.86 Billion by 2033 from a 2026 baseline of $160.21 Billion. Our analysis identifies a CAGR of 8.35%, driven by rapid urbanization and the proliferation of high-end porcelain and glazed ceramic solutions. Strategic consolidation among major global players ensures market stability while fostering innovation in sustainable production.
Market Overview: Definition and Industry Significance
The Ceramic Wall Tiles Market encompasses the manufacturing and distribution of decorative and functional surfaces across residential and commercial sectors. It is a cornerstone of the construction industry, vital for moisture control and aesthetic cladding. From Porcelanosa Group to RAK Ceramics PJSC, market participants cater to stringent architectural requirements, balancing aesthetic versatility with technical performance standards required by global regulatory bodies.
Structural Growth Drivers and Market Restraints
Growth is fueled by a surge in HoReCa and office infrastructure projects globally. However, the market faces logistical hurdles, including the high cost of raw material transport and energy-intensive kiln firing processes. Our analysis suggests that companies leveraging advanced manufacturing to reduce waste effectively navigate these challenges, while strict compliance with ISO international standards remains a prerequisite for market entry and sustained growth.
Emerging Trends in the Ceramic Wall Tiles Market
There is a definitive shift toward large-format porcelain tiles, offering seamless aesthetics with fewer grout lines. Sustainable production is no longer optional; manufacturers like Mohawk Industries Inc. are integrating recycled content to align with green building certifications like LEED. Furthermore, the rise of digitally printed textured finishes allows for unprecedented design customization, directly influencing interior design trends in luxury residential developments.
How did COVID-19 alter the Ceramic Wall Tiles Market recovery trajectory?
The pandemic initially disrupted supply chains, forcing a temporary closure of major production hubs in Italy and Spain. Recovery has been robust, characterized by a shift to digital sales channels and a renewed focus on hygienic, antimicrobial ceramic surfaces for the healthcare sector. Data suggests that the industry demonstrated resilience, with pent-up demand fueling a rapid rebound across major global markets starting in 2022.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high among industry titans such as Grupo Lamosa S.A.B. de C.V. and Roca Corporación Empresarial S.A. Competition centers on product differentiation and geographic reach. Smaller regional players like Kajaria Ceramics Limited thrive by optimizing local supply chains, while premium entities like Ceramiche Atlas Concorde S.p.A. command higher margins through technological superiority and exclusive partnerships with global design houses.
Ceramic Wall Tiles Market Forecast: 2027 to 2033
The market is projected to grow from $160.21 Billion in 2026 to $280.86 Billion by 2033. This trajectory assumes a steady 8.35% CAGR. Growth will be bolstered by infrastructure spending in emerging economies, alongside a replacement cycle in established Western markets requiring energy-efficient building materials. We expect the Porcelain segment to lead this expansion due to its superior durability and lower maintenance requirements.
Segmentation Analysis: Deep Dive into Product and Application
Segmentation provides the blueprint for market penetration. Applications are dominated by Residential and HoReCa, which require diverse aesthetics ranging from handmade terracotta to nano-polished porcelain. By end-user, the focus is shifting toward direct consumer engagement via e-commerce, while Building Contractors remain the primary volume drivers, requiring consistent, large-batch supply of glazed and unglazed ceramic tiles for commercial project execution.
Regional Market Performance and Geographic Distribution
The Asia-Pacific region acts as the primary production engine, while North America and Europe represent critical high-value demand centers. Regional dynamics are shaped by port accessibility—such as the busy transit routes of the Mediterranean for European producers—and localized regulations regarding VOC emissions during tile production. Our analysis indicates that the Middle East continues to be a strategic hotspot for infrastructure-led tile consumption.
In-depth Regional Review: Key Growth Centers
In the Middle East, RAK Ceramics PJSC dominates through massive scale and proximity to major global transit hubs. Conversely, the Indian market, home to leaders like Somany Ceramics Limited, focuses on high-volume residential expansion. Europe remains the hub for R&D and design innovation, with companies like Pamesa Cerámica S.L. setting benchmarks in sustainable manufacturing, influencing global product trends through design-led manufacturing.
Company Profiles: Strategic Positioning of Industry Leaders
Leading companies like Dal-Tile Corporation utilize an extensive distributor network to dominate the North American landscape. Porcelanosa Group positions itself at the top of the luxury tier, emphasizing architectural specification. Meanwhile, players like SCG Ceramics Public Company Limited focus on cost-leadership in the high-growth Southeast Asian market. These companies leverage proprietary technology and global logistics to maintain competitive parity within the fragmented ceramic tile industry.
Porter's Five Forces Analysis of the Market
The industry faces moderate supplier power, restricted by the availability of high-quality clay and feldspar. Competitive rivalry is intense, particularly regarding pricing and innovation in finish techniques. The threat of substitutes—such as vinyl and laminates—is present but limited by the intrinsic durability and thermal properties of ceramic. Overall, the high capital expenditure required for kiln operations creates significant barriers to entry for new players.
SWOT Analysis of the Ceramic Wall Tiles Market
Strengths: Ubiquity and high durability. Weaknesses: High carbon footprint and energy sensitivity. Opportunities: Rapid expansion in healthcare-grade antimicrobial tiles and smart-home building materials. Threats: Fluctuating raw material prices and stringent carbon emission regulations. Our analysis shows that companies that proactively pivot toward decarbonized manufacturing are best positioned to leverage these opportunities while mitigating long-term structural threats to their business models.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with the extraction of natural minerals, followed by high-temperature processing. Strategic value is added at the design and glazing stage, where digital printing enhances product margins. Logistics, particularly maritime shipping via major ports, link manufacturers like White Horse Ceramic Industries Sdn. Bhd. to global distributors and end-users, ensuring that the $280.86 Billion market remains highly connected and efficient.
Investment Insights and High-Potential Areas
Investors should target companies investing in energy-efficient kilns and circular economy initiatives, such as recycled glass-ceramic blends. The Healthcare and Office sectors offer high-margin opportunities for manufacturers of specialty-finish porcelain that meets medical sanitization standards. Based on our data, geographical focus should prioritize rapid urbanization zones, where infrastructure development mandates continuous, high-volume supply of reliable glazed ceramic tiles.
Conclusion and Key Takeaways for Stakeholders
The Ceramic Wall Tiles Market is in a period of sustained, profitable expansion. With a CAGR of 8.35%, the sector's evolution toward sustainability and high-tech aesthetics creates a distinct divide between market leaders and followers. Success depends on the agility to adapt to regional building codes, the ability to manage raw material volatility, and a commitment to product innovation that addresses the evolving needs of the residential and commercial sectors.
Research Methodology: How are estimates triangulated?
Our estimates are derived from triangulation: cross-referencing national trade registry data with primary stakeholder interviews and macroeconomic indicators from major construction bodies. We analyze historical shipment volumes, port data, and company financial disclosures. This rigorous methodology ensures that our $280.86 Billion forecast is rooted in grounded industry realities, accounting for inflationary pressures and shifting geographic demand patterns.
Scope of the Report and Coverage Parameters
This report examines the Ceramic Wall Tiles Market through 2033, covering technical specifications including porcelain, terracotta, and glazed ceramic. While the scope focuses on global market dynamics, it specifically highlights regional trends in North America, Europe, and APAC. Limitations include the exclusion of artisanal non-commercial handicrafts, focusing exclusively on industrial-grade production that impacts the aggregate market size and competitive landscape.
Recent Developments: Strategic Moves and Launches
Recent activity is marked by strategic acquisitions to consolidate supply chains and product launches focusing on large-format, ultra-thin porcelain. Notably, industry leaders like Florida Tile Inc. have pivoted toward carbon-neutral production lines. These announcements signal a clear industry-wide move toward environmental transparency and the adoption of Industry 4.0 standards in manufacturing, as evidenced by recent partnerships between major tile producers and automated kiln technology innovators.